YOUR HOME SOLD GUARANTEED OR WE'LL BUY IT!*
October 2026: Calgary Real Estate Market Sees Slower Sales and Shifting Prices
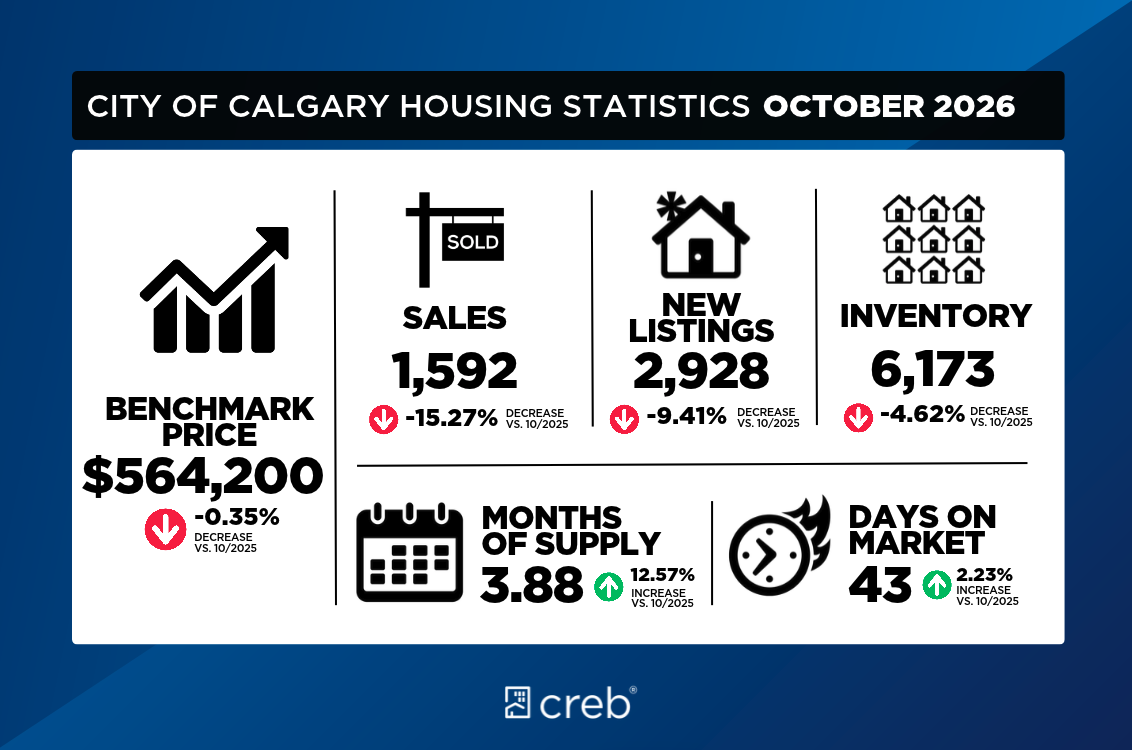
Calgary’s real estate market continued to slow in October 2026, with 1,592 sales recorded, contributing to an almost 11% decline in year-to-date sales. Falling new listings helped reduce inventory levels, which were nearly 5% lower than October 2025. However, market conditions varied by property type, with detached and semi-detached homes remaining relatively balanced while apartment condominiums and row homes faced greater competition and higher supply. Overall, Calgary’s benchmark prices remained close to year-ago levels, although year-to-date prices were nearly 3% lower.
Detached homes recorded 847 sales in October, nearly 16% fewer than the previous year. The benchmark price was $735,100, less than 1% lower than October 2025. Semi-detached homes showed greater stability, with sales improving from September and the benchmark price reaching $685,200, nearly 1% higher than the previous year. Year-to-date prices for semi-detached homes remained relatively unchanged, reflecting tighter market conditions compared with other property types.
Row homes and apartment condominiums continued to experience the greatest downward pressure on prices due to elevated inventory and competition from new homes and rental options. The row-home benchmark price fell to $407,500, more than 5% lower than October 2025, while apartment condominiums reached $288,800, an 8% year-over-year decline and 15% below their August 2024 peak. Apartment condominiums continued to face more than five months of supply, while row homes reached 4.4 months, indicating more buyer-favourable conditions in these segments.
In surrounding communities, Airdrie experienced a 13% year-to-date decline in sales, with its detached benchmark price falling to $587,300 and overall prices down nearly 5% year to date. Cochrane remained stronger in sales, with year-to-date activity nearly 4% higher than in 2025, although its benchmark price declined to $571,100, nearly 2% below the previous year. Both communities faced increased competition and greater supply, contributing to downward pressure on prices.
Okotoks continued to experience relatively balanced conditions, with three months of supply and year-to-date benchmark prices approximately 1% lower than last year. Chestermere faced more elevated inventory, with supply remaining just below six months and its October benchmark price reaching $683,800, more than 3% lower than October 2025. Despite recent price declines, year-to-date prices in both Okotoks and Chestermere were only about 1% below 2025 levels. Overall, Calgary and its surrounding communities offer varying opportunities for buyers, with greater negotiating power in higher-supply markets and more stable conditions in detached and semi-detached segments.